

What Happened
Three things are changing at once in the AI data center outlook (ignoring the quickly changing data center engineering dynamics and its implications for memory, which I will return to on Friday).
Execution risk is rising sharply. There are new estimates that as much as half of planned U.S. data-center capacity may be delayed or never built. Requiring deposits is causing projects to drop out of the queue in large numbers.\
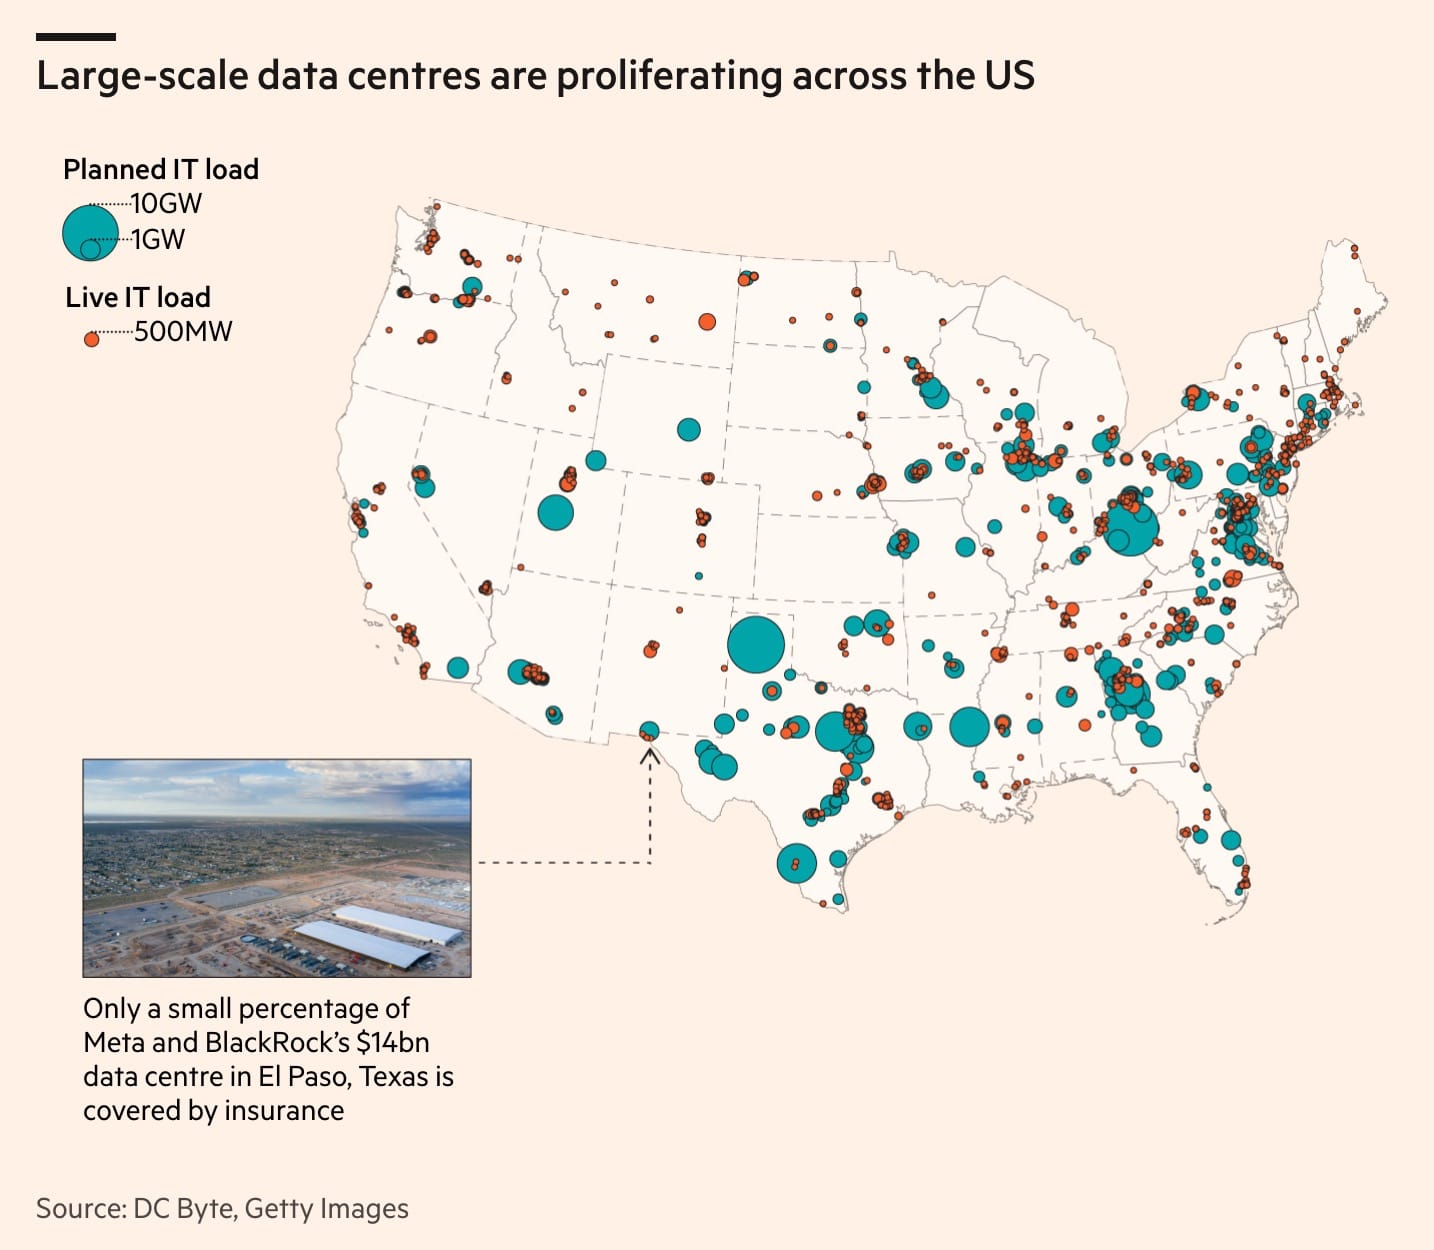
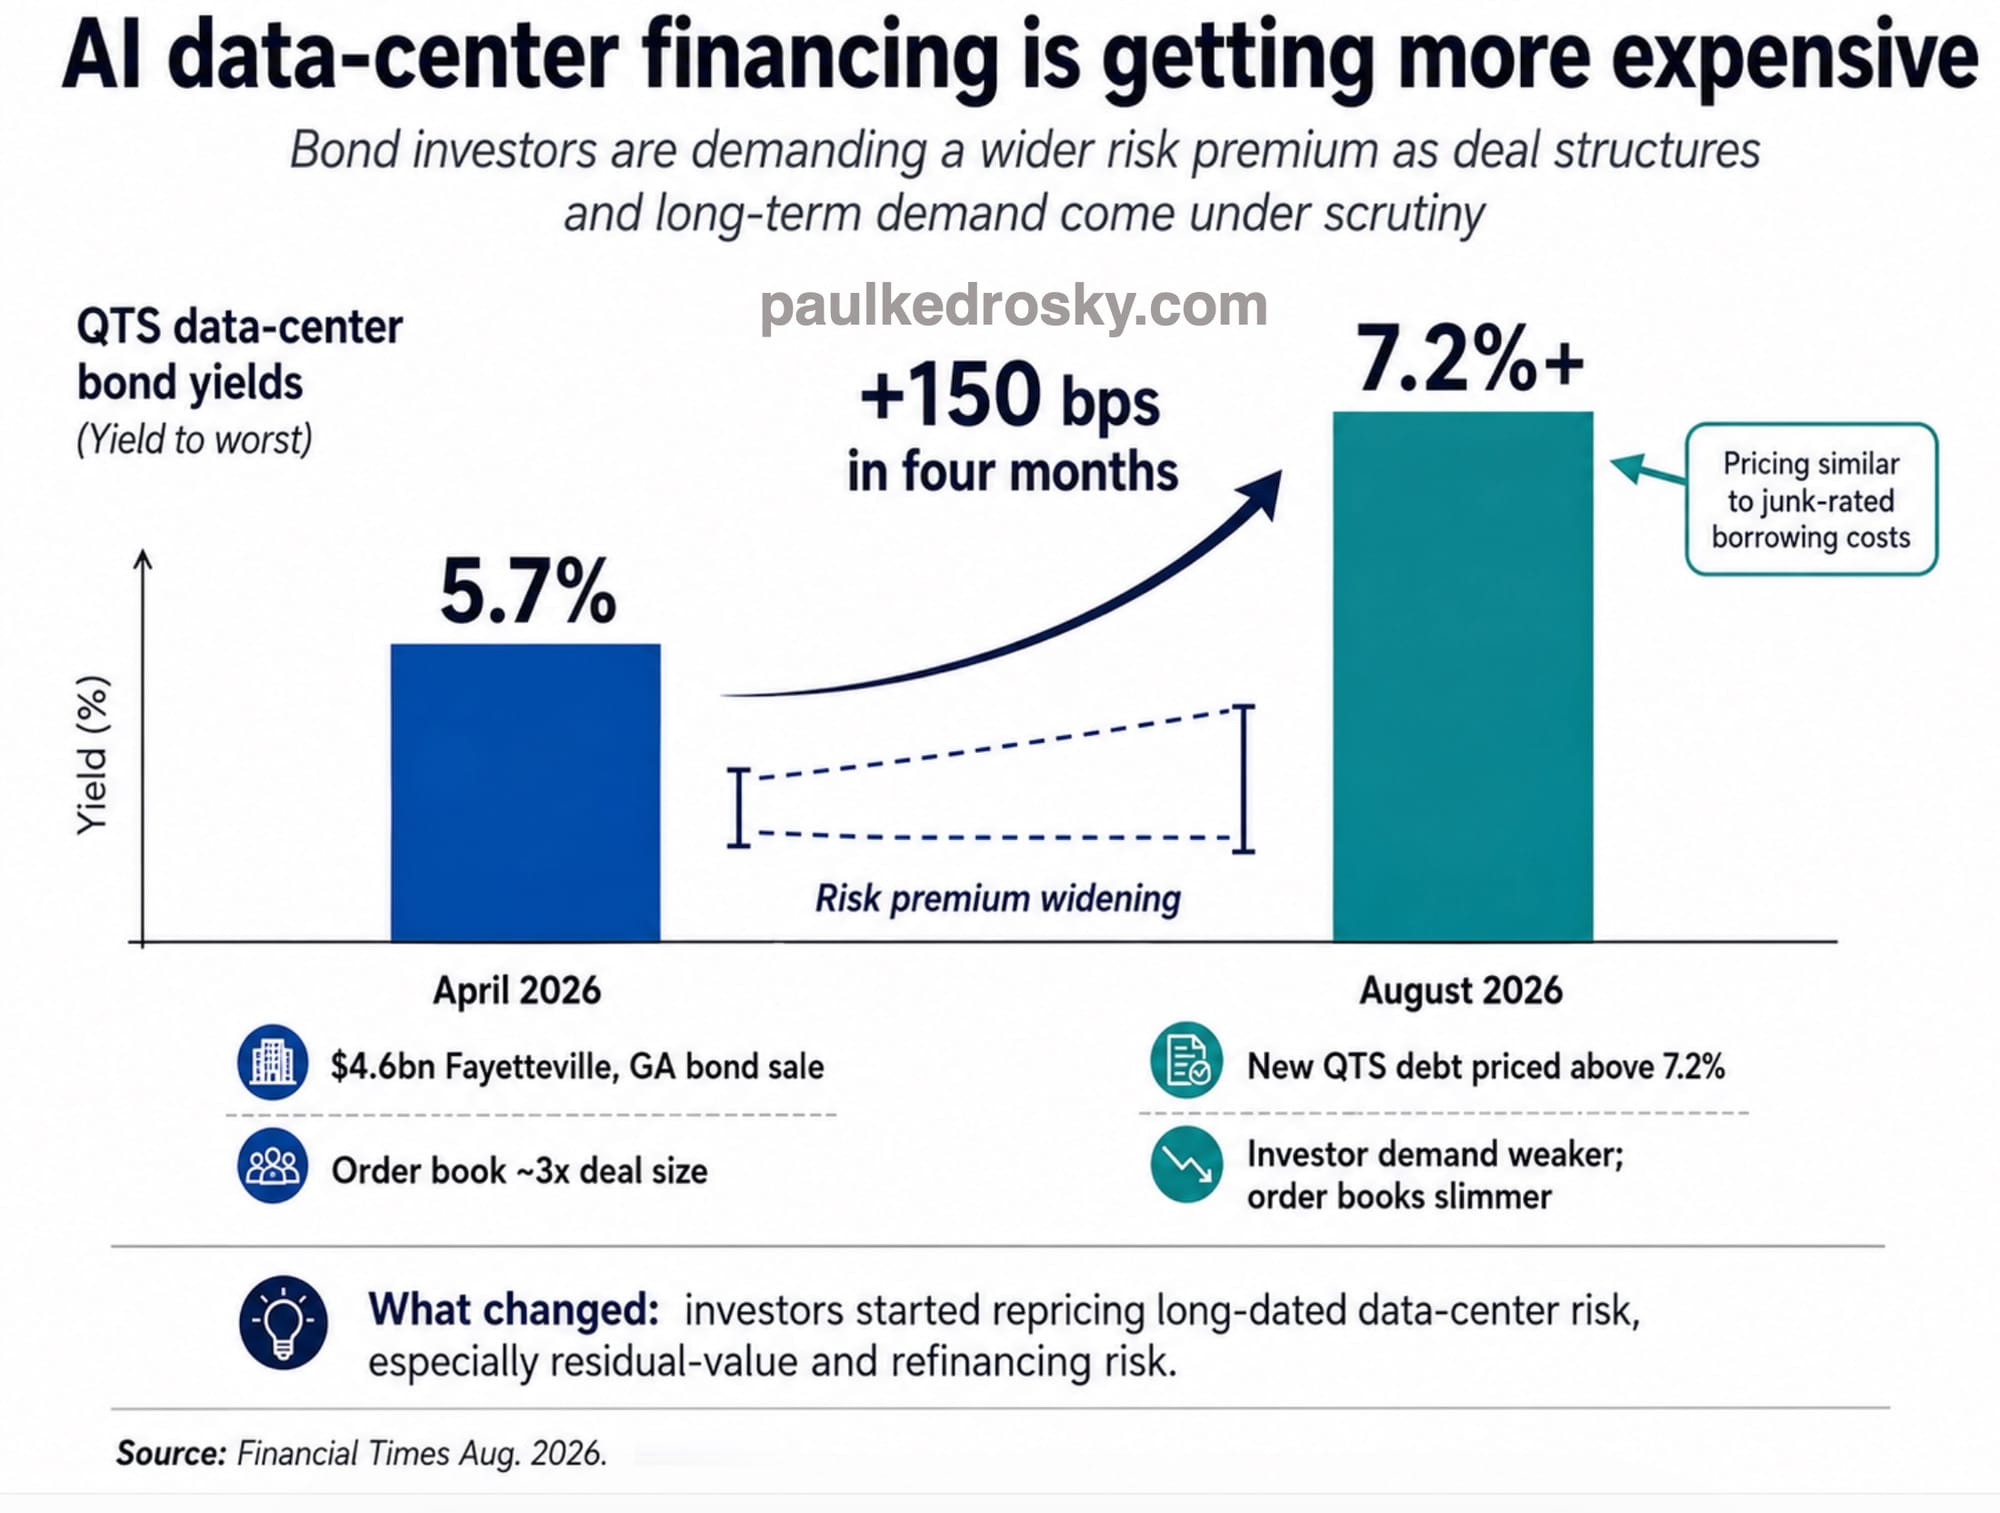
Financing is becoming less forgiving. Lenders and investors are reassessing leverage, residual values, lease durability and the risk that assets financed against long-lived assumptions become economically impaired much sooner.
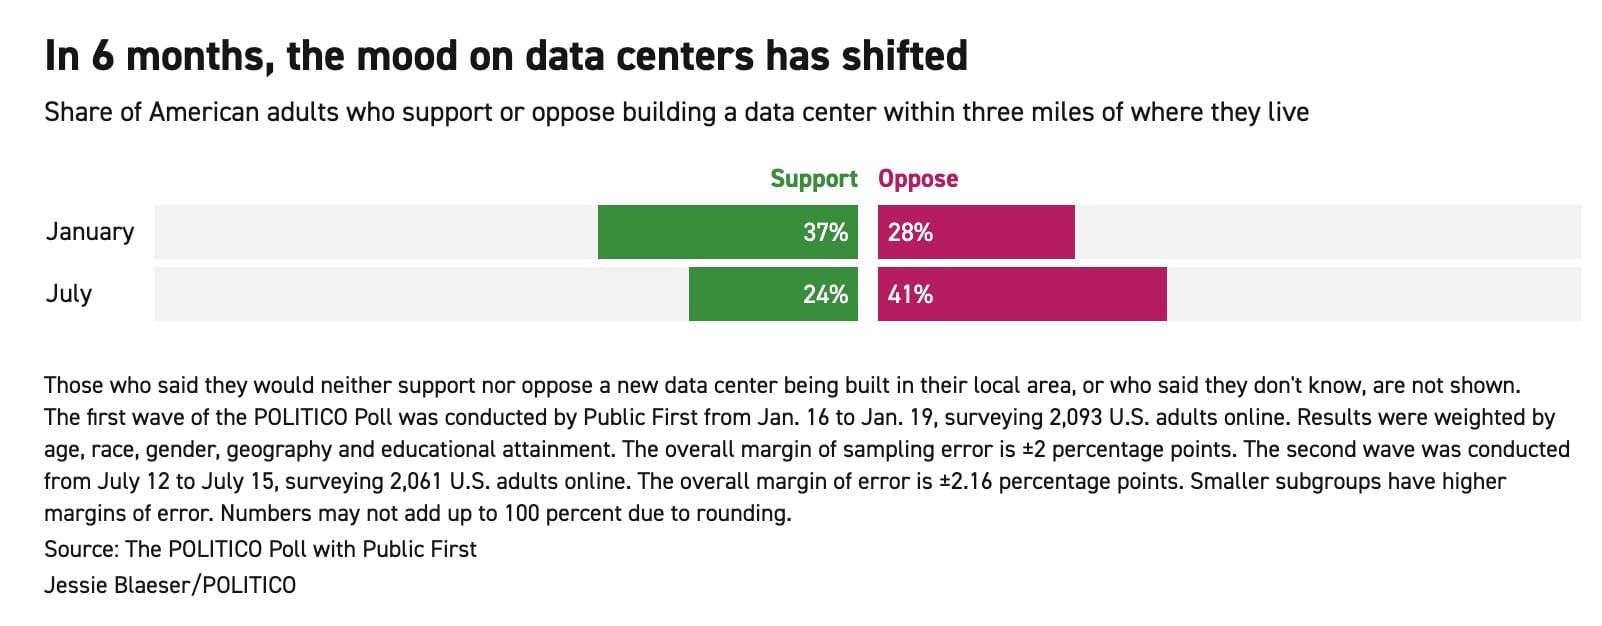
Political risk has increased sharply. Local opposition is hardening into moratoriums, stricter permitting, politicians are all flipping to more negative, and infrastructure charges are growing as the pipeline brakes come on,
None of these is new individually, but the interaction is changing the data center tenor.
What It Means
The market has been valuing much of the announced data-center pipeline as though it were effectively committed. That assumption now looks too aggressive, with half of projects unlikely to ever start, and another sizable fraction disappearing when forced to make deposits.