

Four things worth thinking about this evening:
- South Korea leverage unwind.
The following Scooby Doo statistic made the rounds today, and, while an exaggeration, it is directionally useful in showing the extent of the margin unwind in memory-related semiconductors.
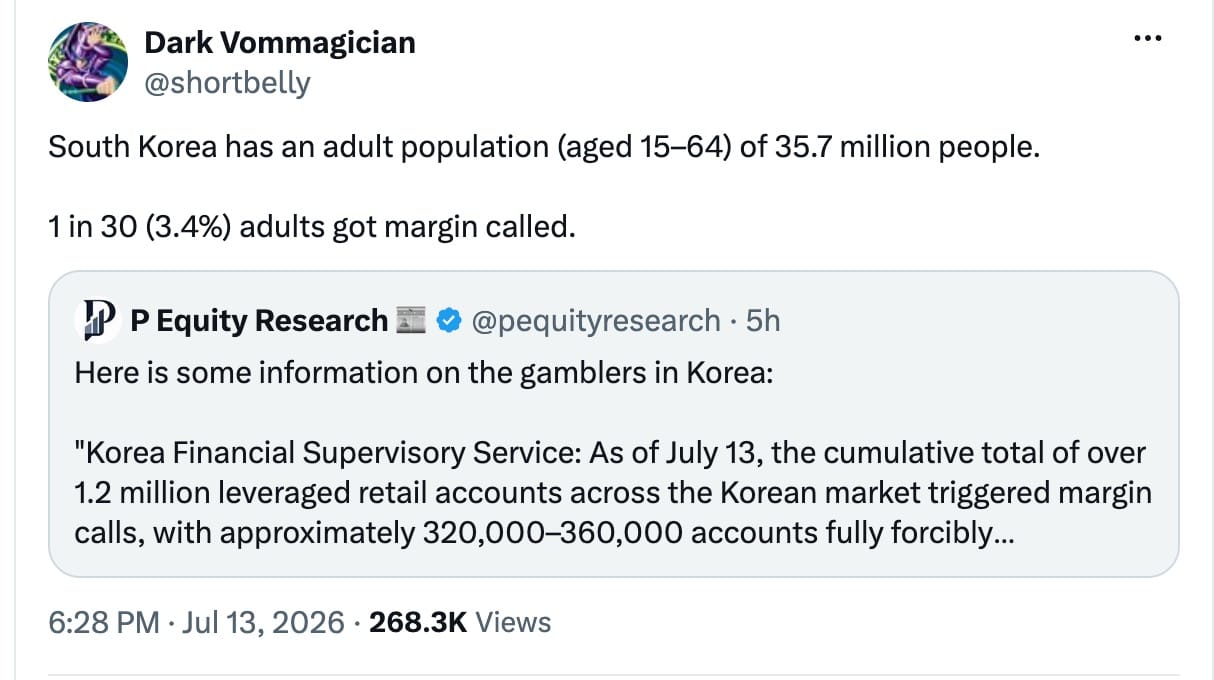
A million margin calls here, a million margin calls there, and it starts to add up. More seriously, I have not found a credible source for this beyond the various X/LinkedIn accounts—many likely AI—that are repeating one another in an algorithmic dogpile. The headline math is also a mess. For example, it equates a brokerage account to a single adult, which is almost certainly wrong.
Nevertheless, what do we know? We know South Korean investors are epically over-exposed to a triple-leveraged, US-listed ETF, and that said ETF has declined by half in the last month (after a big run), and that fall has systemic & reflexive consequences.
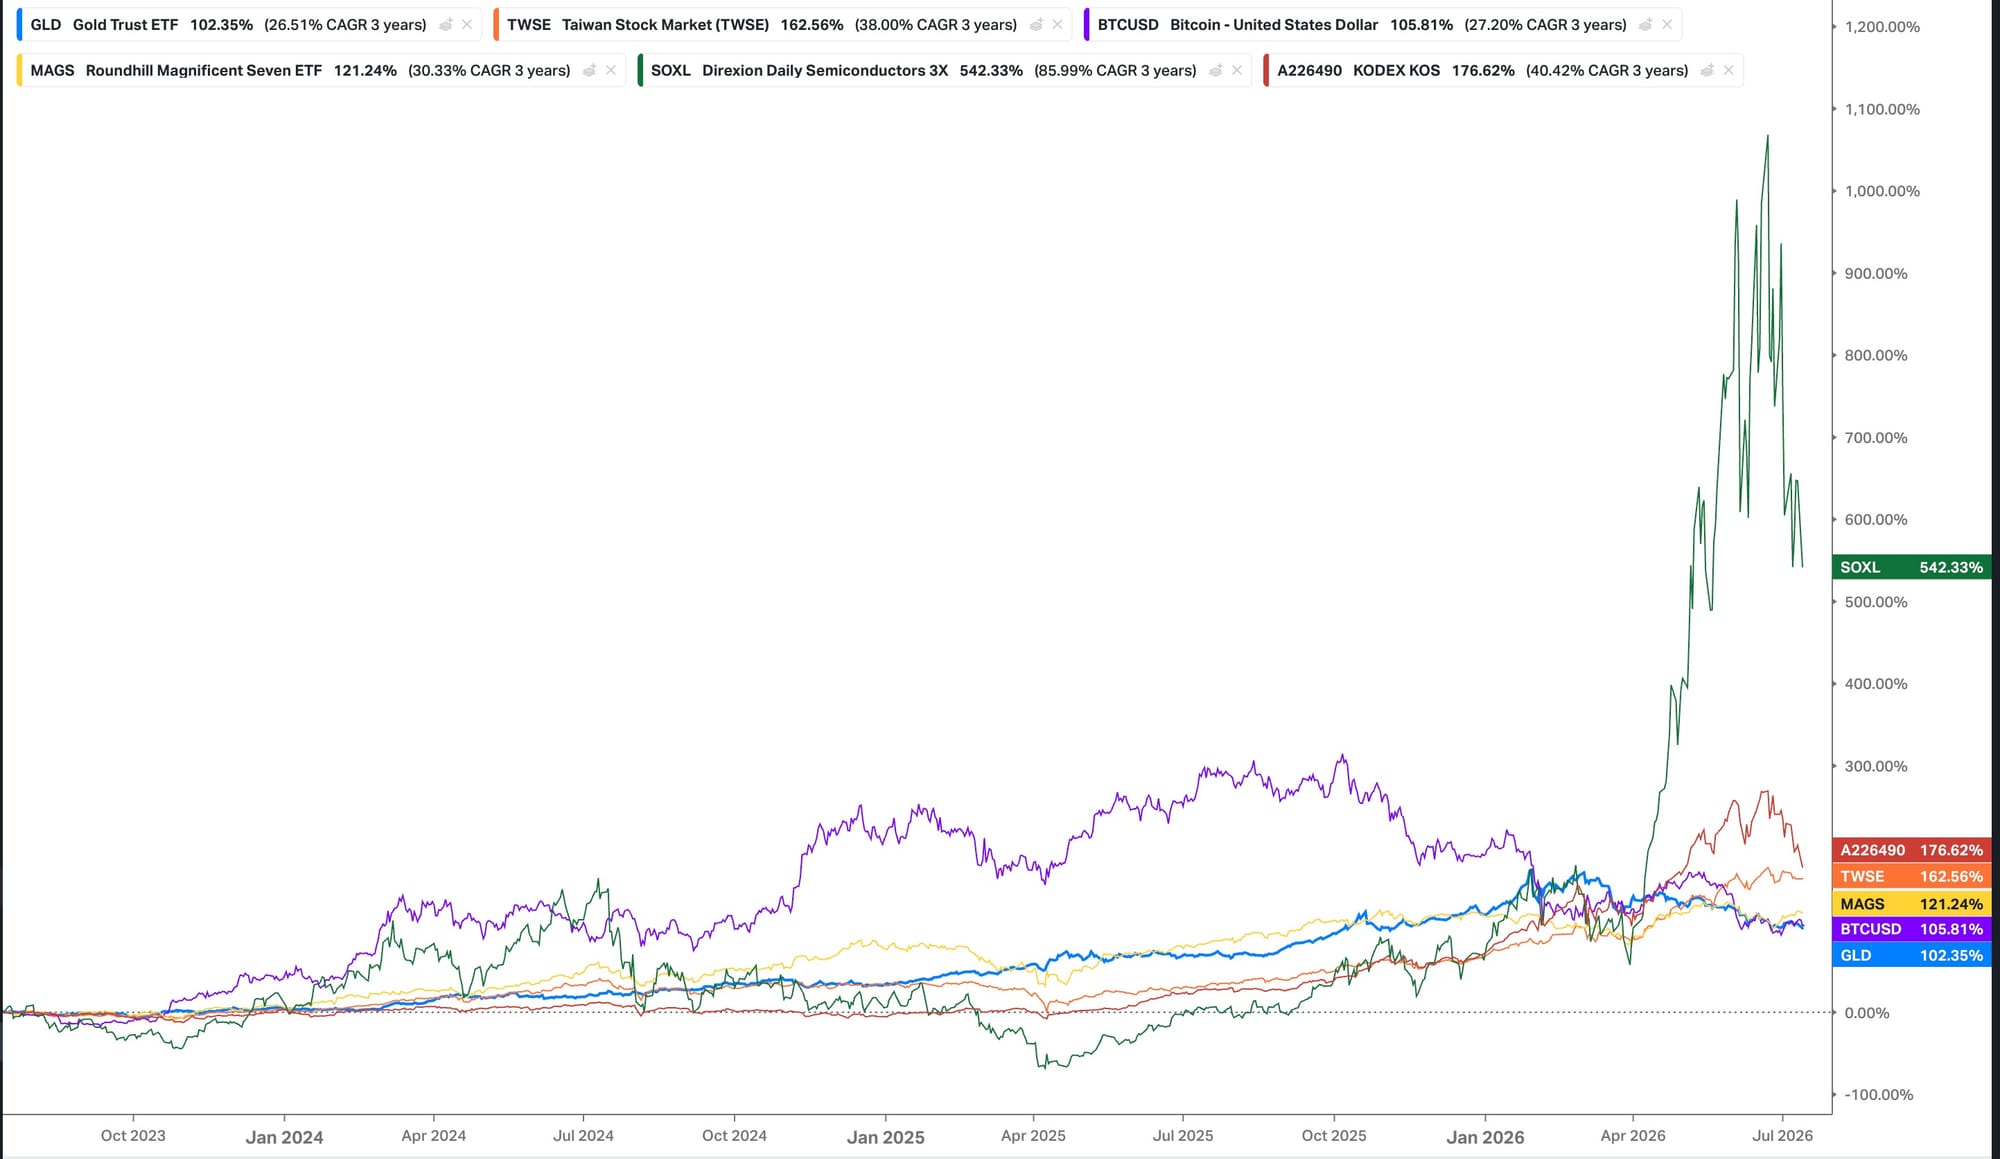
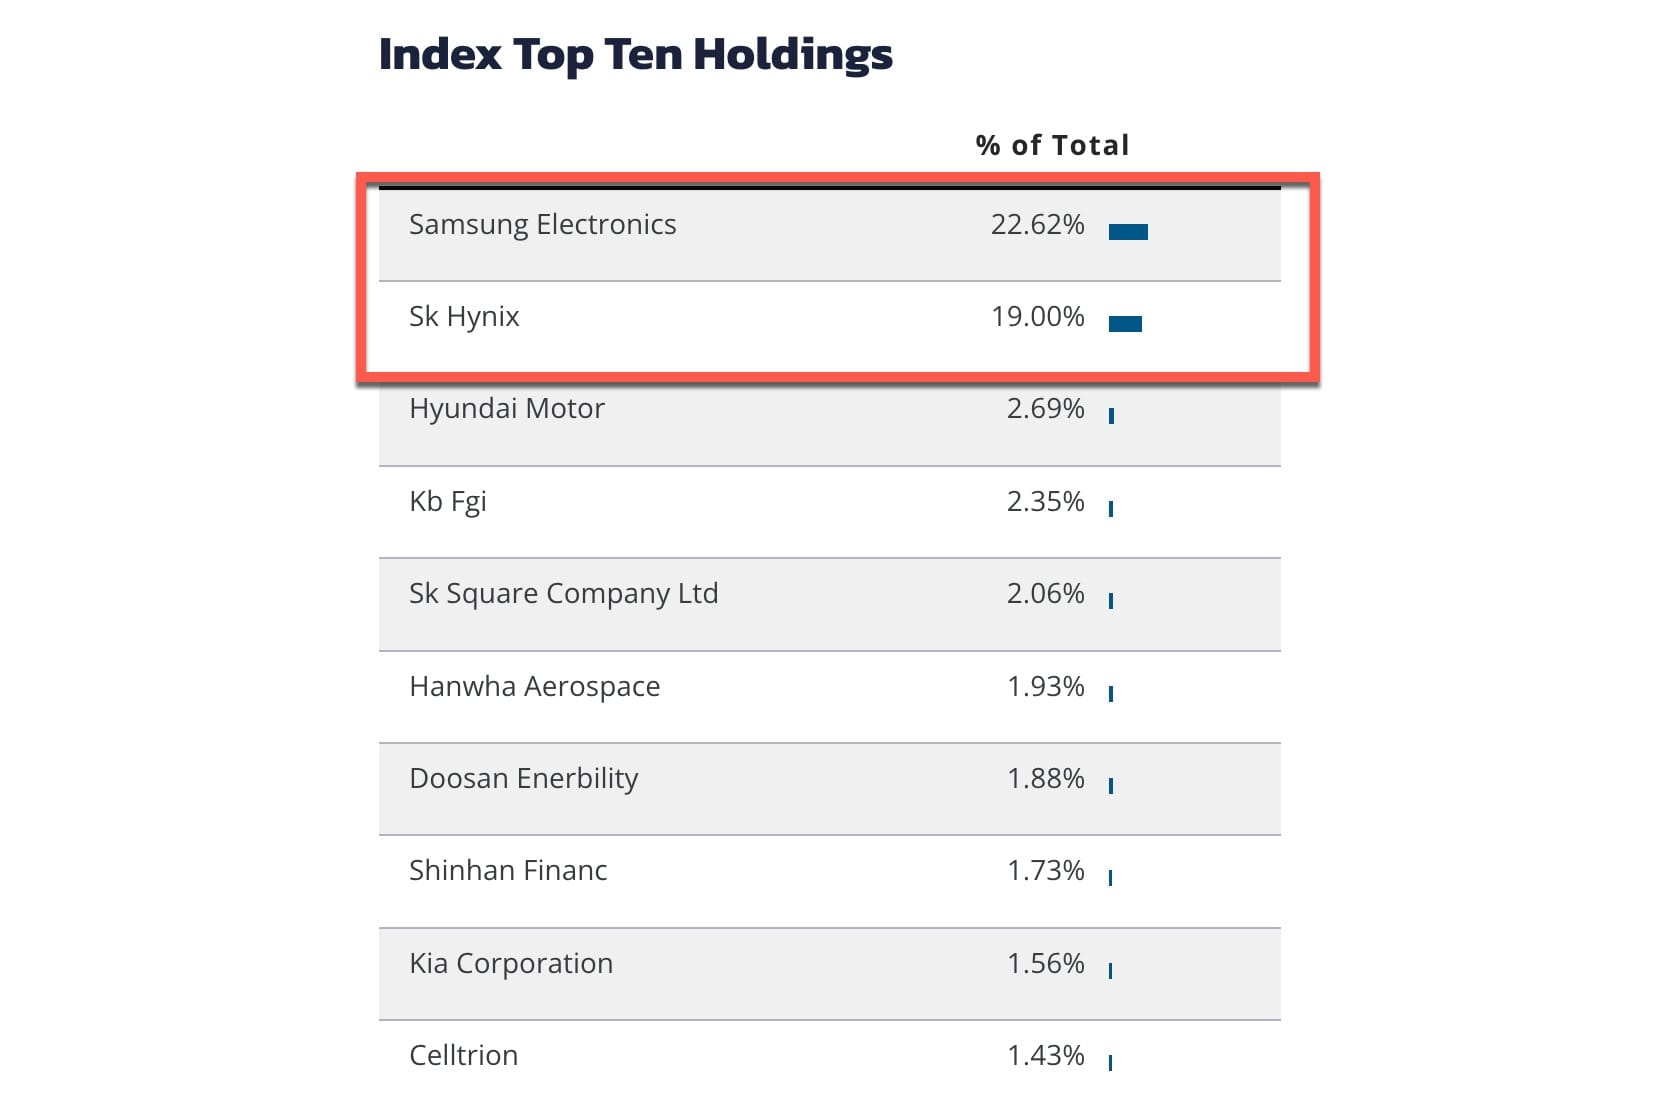
Which leveraged instrument? The main driver is a US-listed leverage ETF—Direxion's triple-leveraged ETF: SOXL—whose holdings are ... highly concentrated. Two companies comprise almost half its total, and they are proxies for the same thing: memory prices.
What, you may wonder, are South Korean investors doing in a US-listed triple-leveraged ETF. Well, while such triple-leveraged ETFs are not listed on Korean exchanges, Korean investors can "invest" in them after a one-hour leveraged-ETF investor education (costing around $3) requirement.