

The following Friday roundup describes an increasingly narrow system: capital and confidence are concentrating around AI and its infrastructure, while strain builds ... everywhere, from public markets, to sovereign debt, to the consumer economy.
Here is what's ahead:
- Tech Dominates the S&P 500 — Concentration surpasses the dot-com peak
- AI's Growing Debt Appetite — Hyperscalers reshape bond markets
- AI Scaling Approaches Human Efficiency — The cost of longer autonomous tasks collapses
- Anthropic IPO Uncertainty — Prediction markets price further delays
- IPO Cancellations Surge — September withdrawals hit a five-year high
- Getty's AI Reckoning — Generative AI undermines image licensing economics
- Consumer Confidence Collapses — Household sentiment approaches historic lows
- France's Sovereign Debt Stress — Rising spreads threaten euro-area contagion
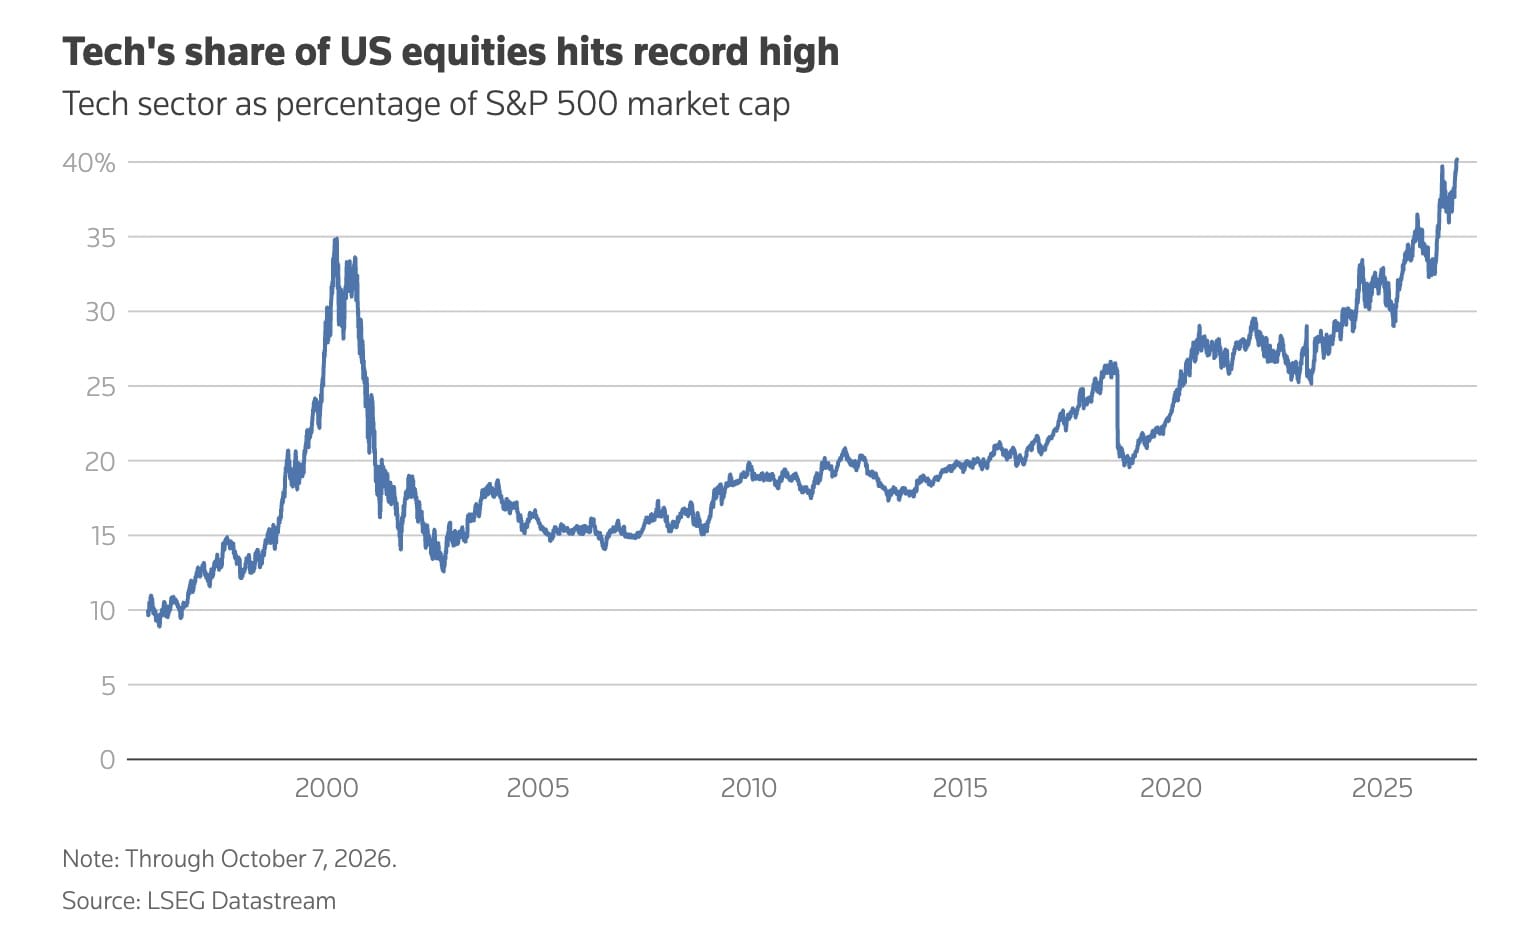
Tech was already the market; now it is even more so. The sector has reached roughly 40% of S&P 500 capitalization, surpassing the dot-com peak. This is not merely a valuation story. Index performance, retirement assets, corporate investment, and the wealth effect are becoming increasingly dependent on one interconnected technology trade.
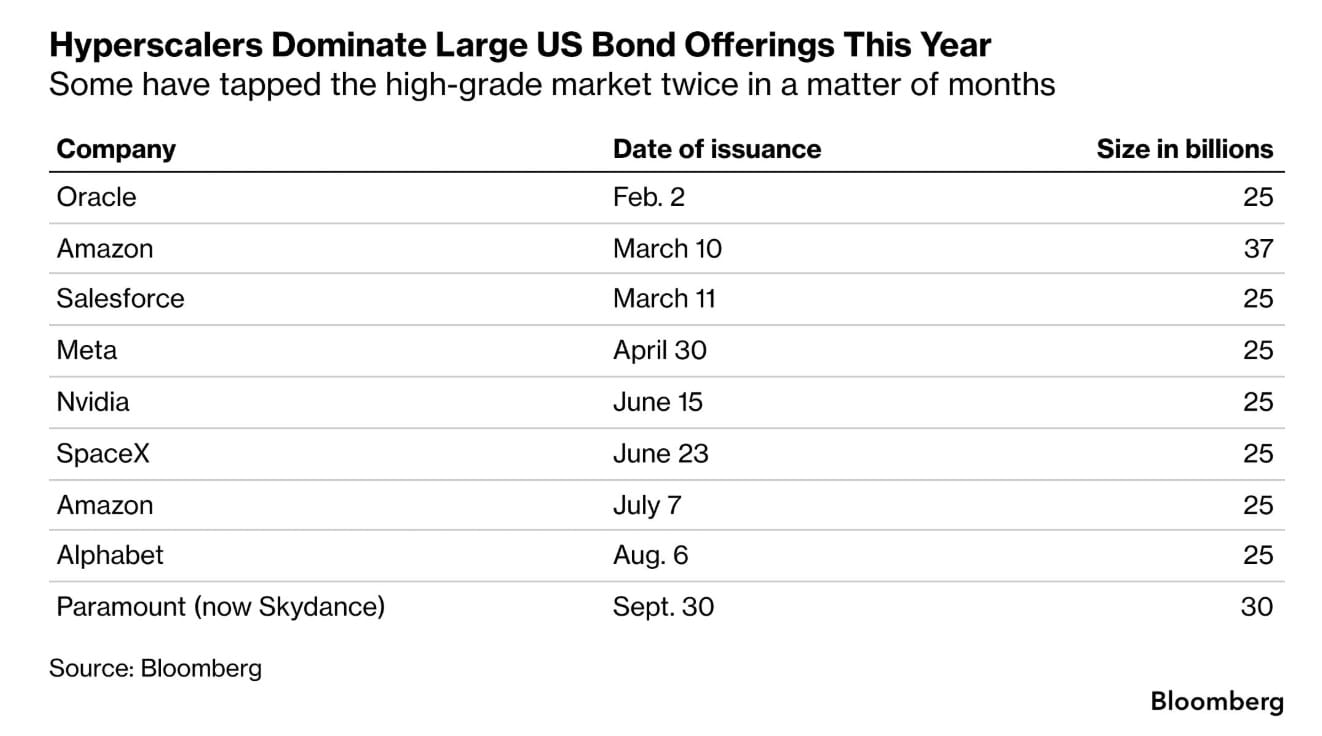
That concentration requires enormous amounts of capital. Hyperscalers dominate the year’s largest bond offerings, sometimes returning to the market within months. The AI buildout is no longer being financed from cash flow alone: its capital requirements are beginning to reshape the investment-grade debt market.
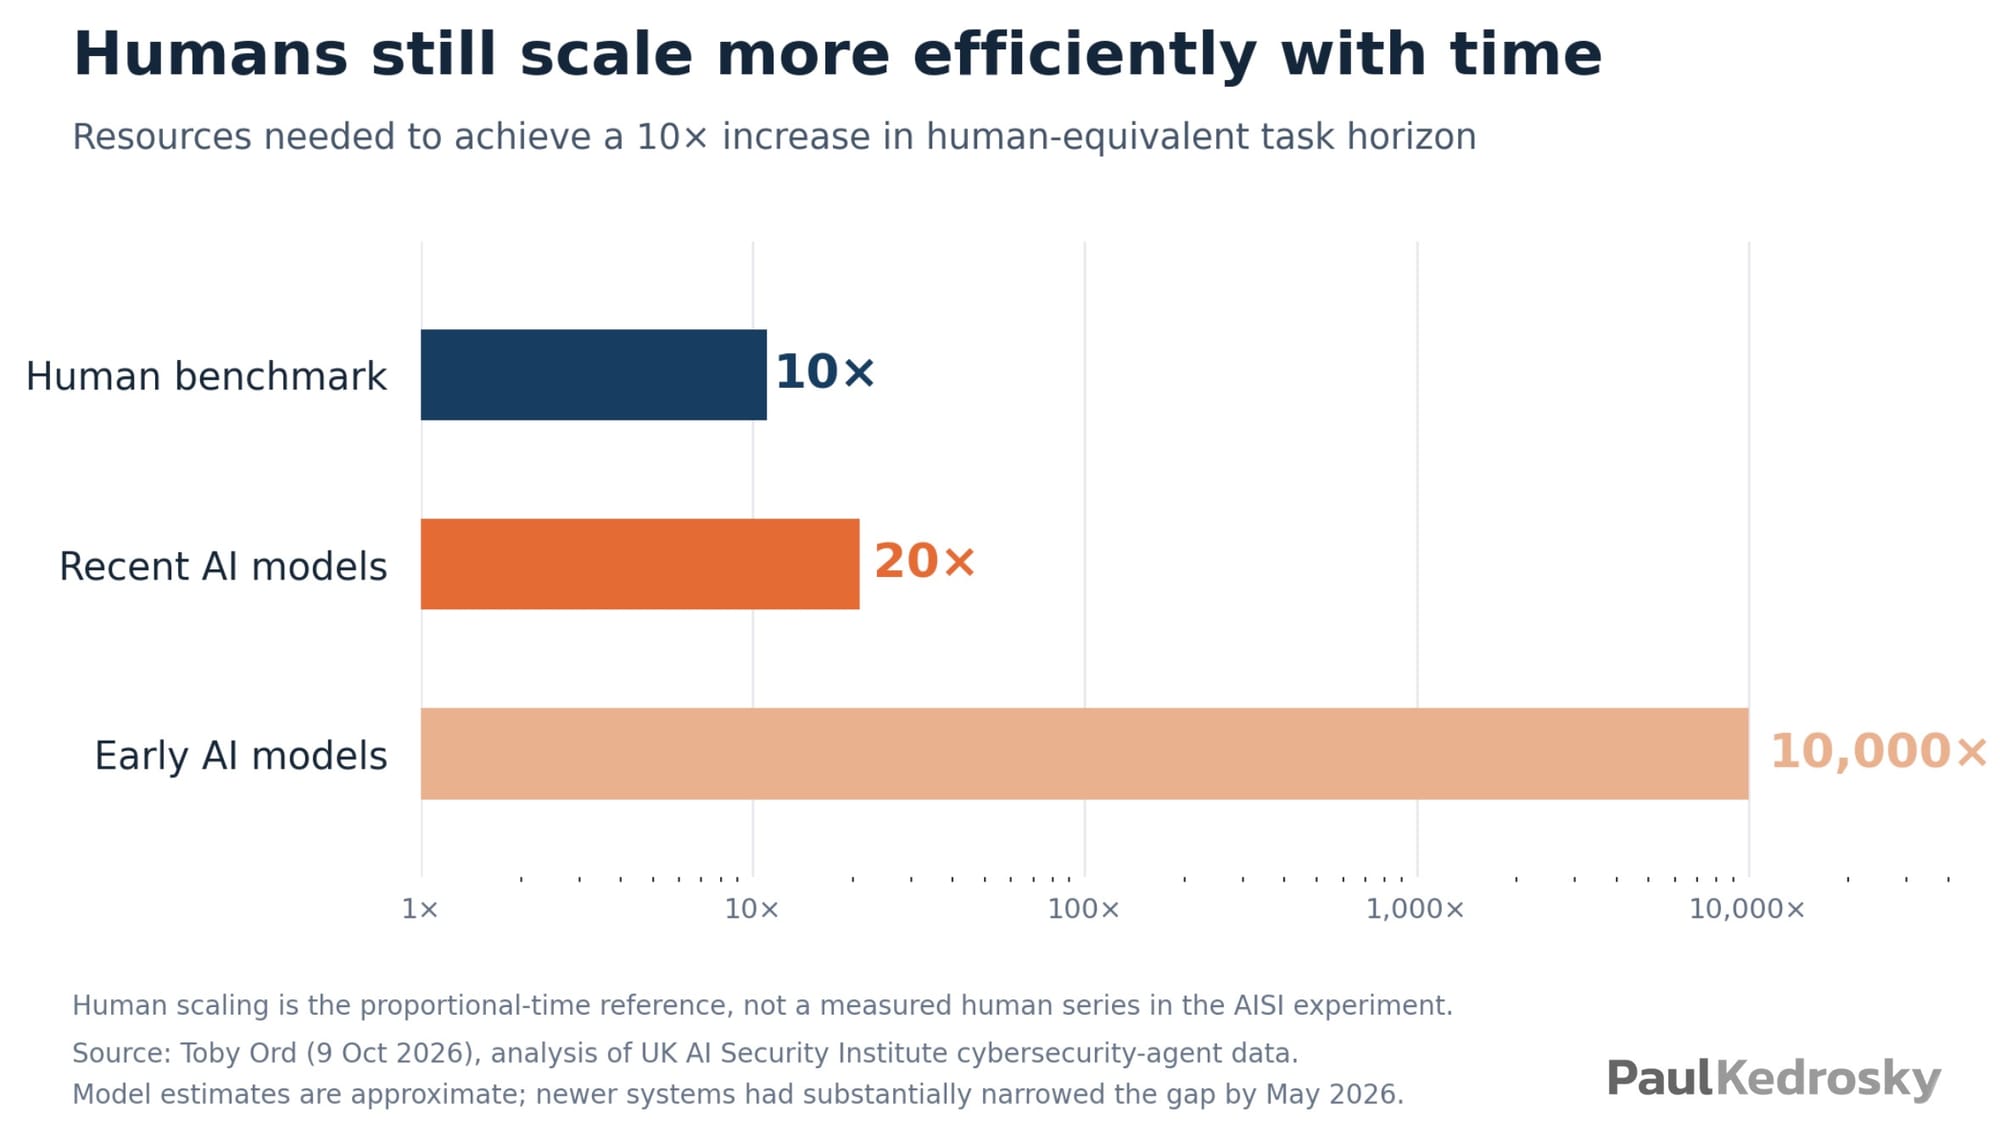
AI capability is also becoming radically cheaper to extend. Early models required roughly 10,000 times more resources to achieve a tenfold increase in task horizon; recent models need closer to 20 times, versus the human benchmark of 10. The remaining efficiency gap is now small enough that longer autonomous work becomes an engineering and deployment question, not a distant theoretical one.
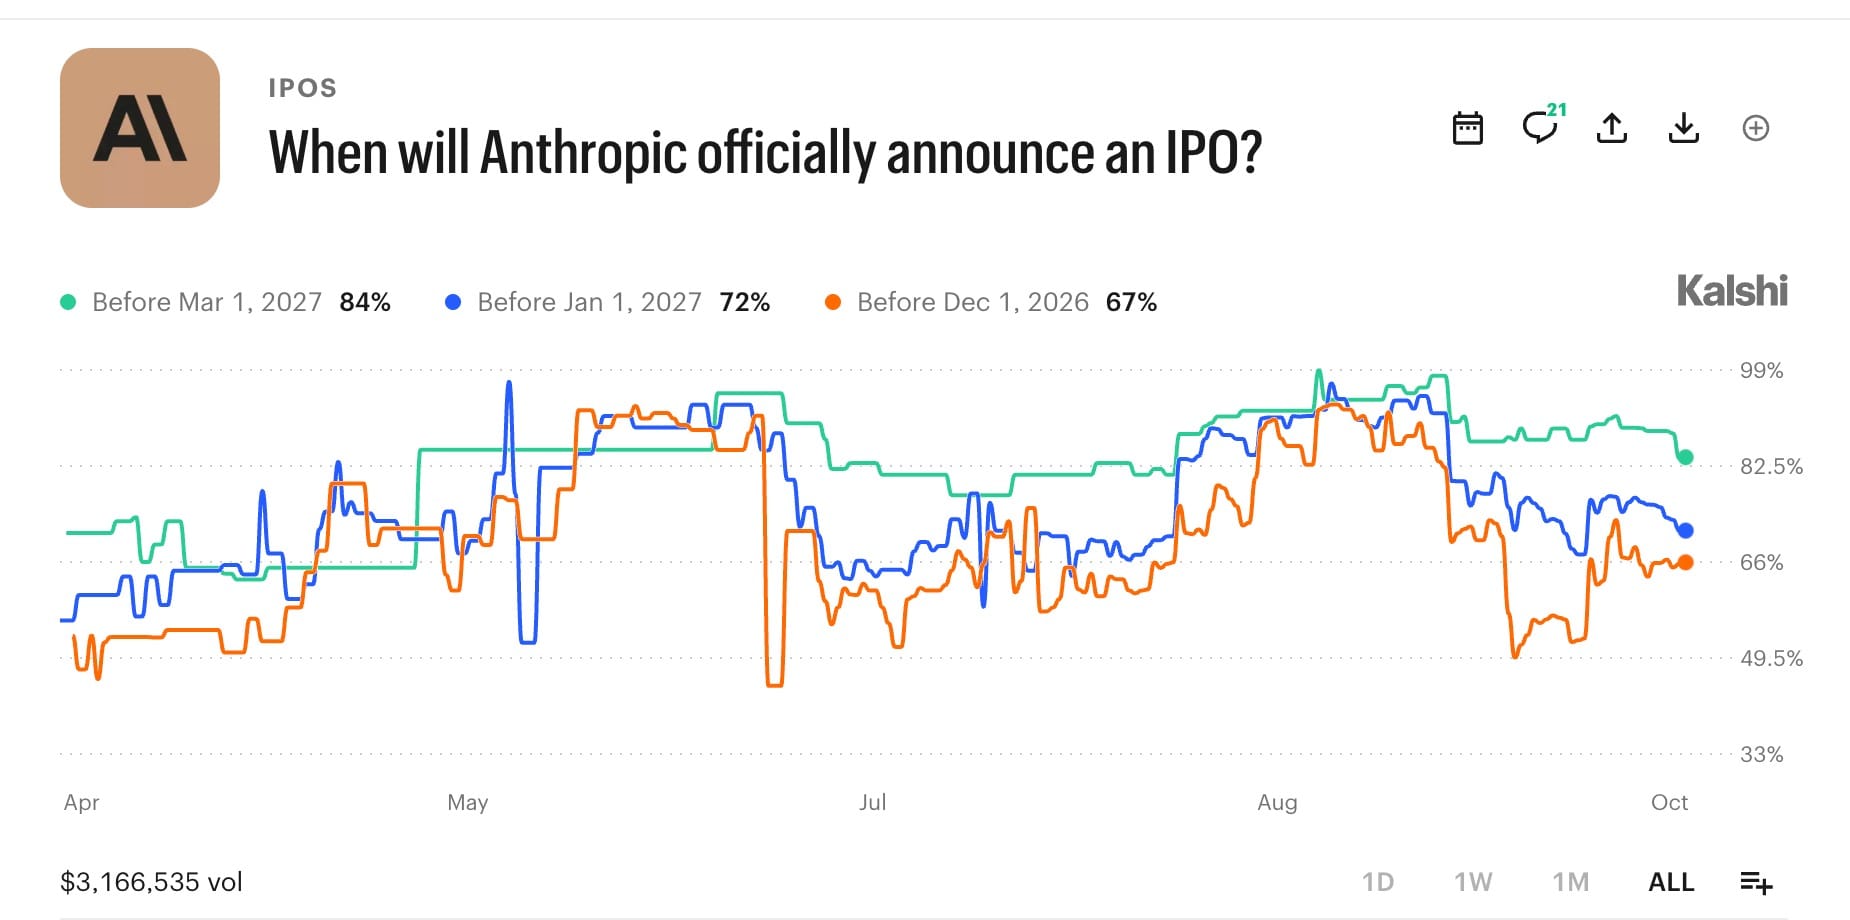
Markets remain skeptical about Anthropic’s IPO timetable. Despite an announcement being expected within weeks, prediction markets still price a substantial chance that it will not happen by then. The odds rise only as the deadline extends into 2027—a market pricing slippage, not inevitability.
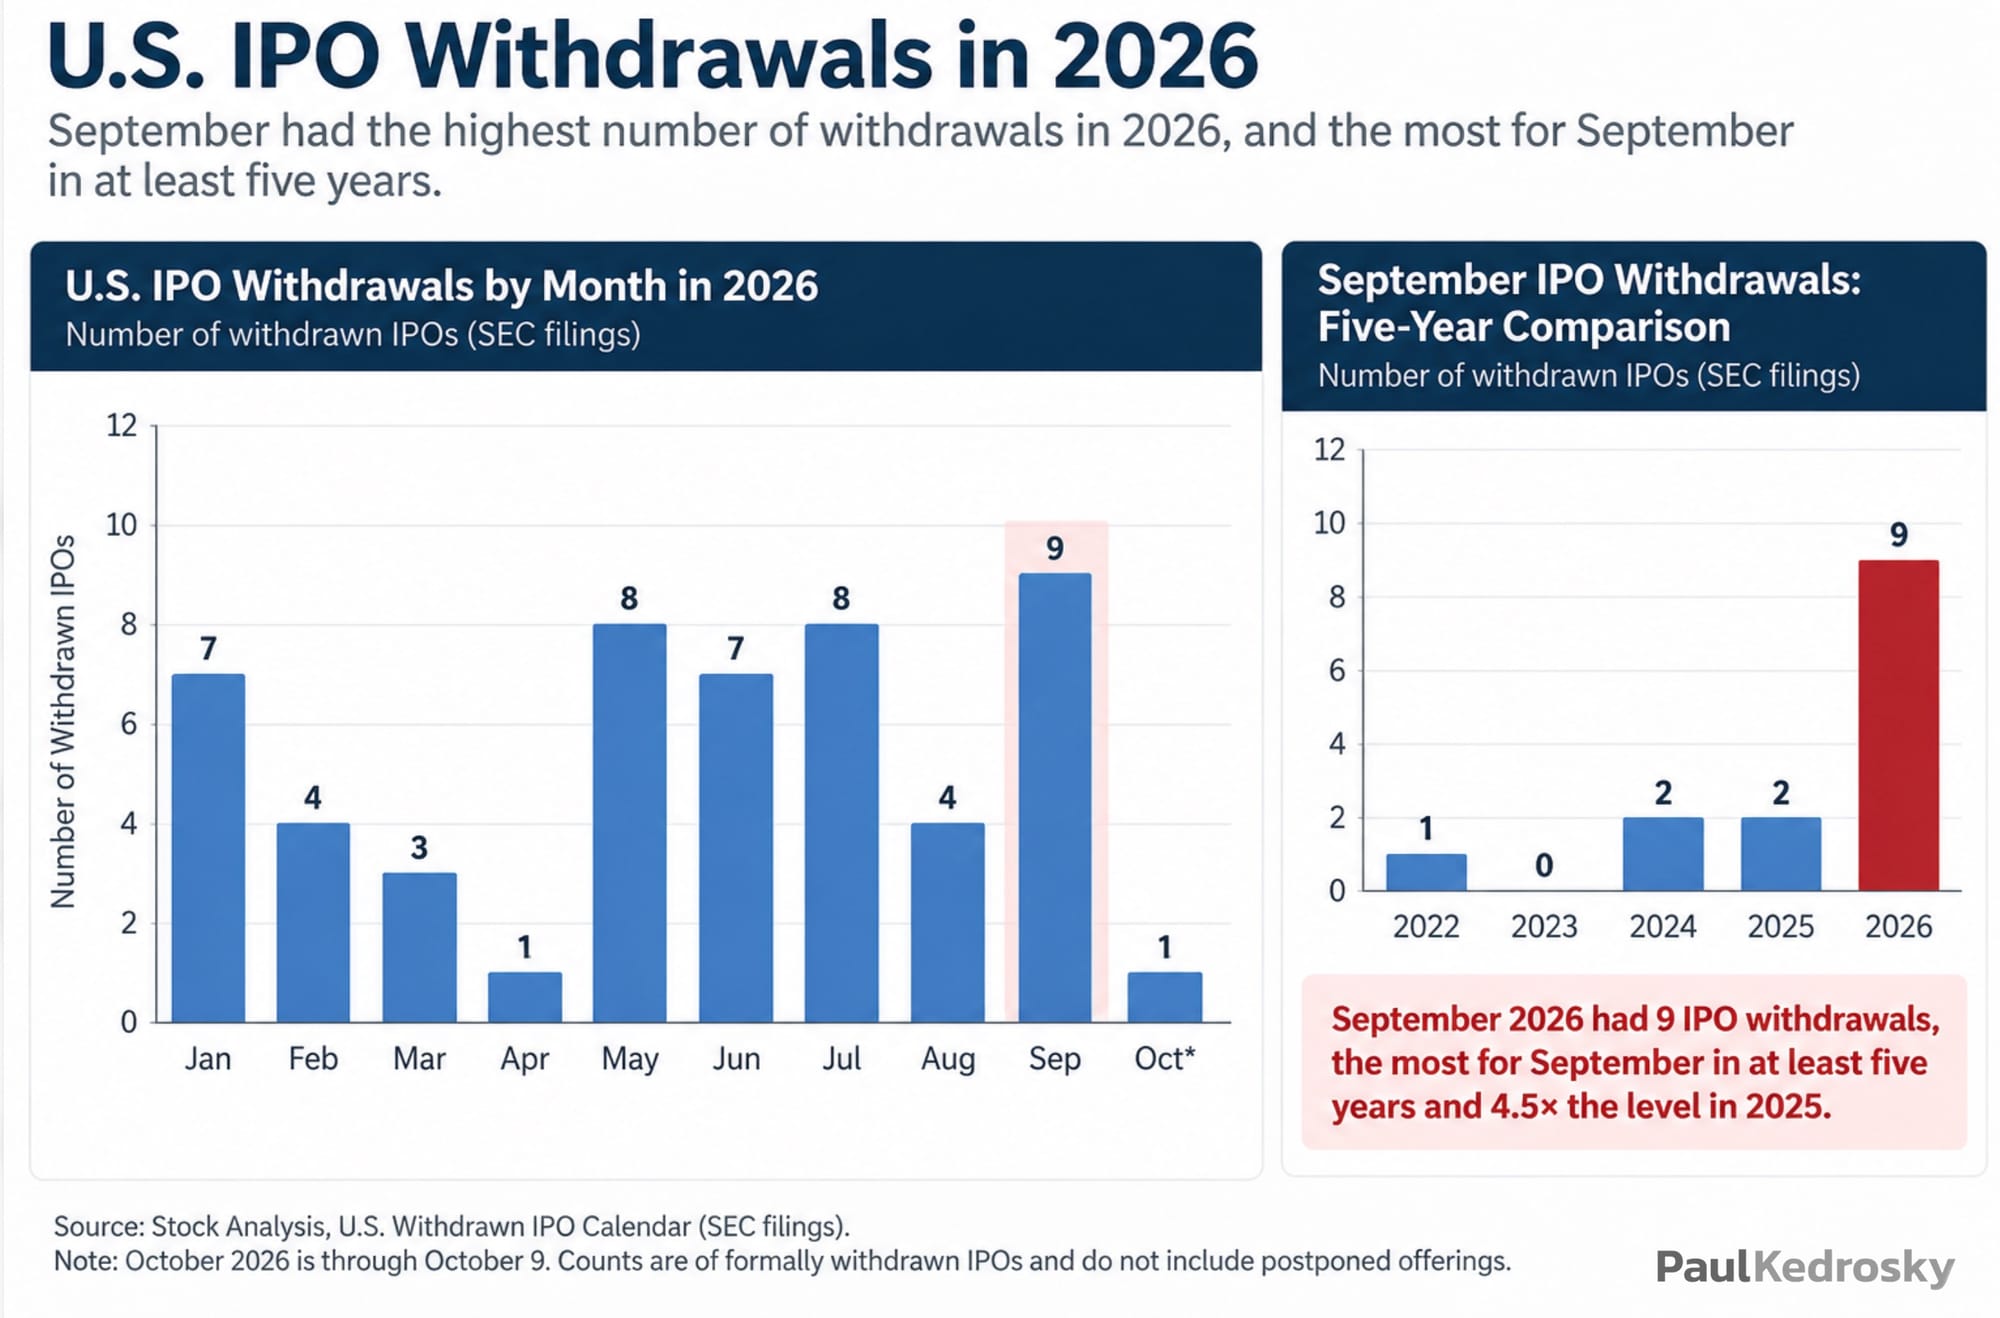
IPO withdrawals are at record levels. September produced nine cancellations, the most for that month in at least five years and 4.5 times the 2025 total. Delays and withdrawals are accumulating even as a small group of AI companies commands extraordinary private valuations and investor attention.